For years, home insurance in the Bay Area was the quiet line item at the bottom of a transaction - assumed, arranged, and rarely discussed. That has changed. Across Marin's coastal and wildland communities especially, insurability now shapes what a home costs to own and how smoothly it trades.
This fall brings a concrete example. California's FAIR Plan, the state's insurer of last resort, is adjusting its dwelling rates, and the number is worth understanding well before you write an offer or renew a policy. The encouraging part: with a little foresight, it's entirely manageable.
How much are FAIR Plan rates going up?
Beginning October 15, 2026, the California FAIR Plan is implementing a statewide average dwelling rate increase of 29.1% for new and renewing policies. It's an average, not a flat rate - the largest share of the increase relates to the wildfire portion of a premium, so higher-risk properties will see more, lower-risk ones less, and some policyholders may even see a decrease.
Context matters here, and it's genuinely reassuring: the plan originally sought 35.8%, and the California Department of Insurance brought that down to 29.1%. This was also the first FAIR Plan filing reviewed under the state's new Sustainable Insurance Strategy, which allows wildfire catastrophe modeling and some reinsurance costs to be weighed in rate review - the same framework intended, over time, to draw private insurers back to California homeowners.
Why rates are rising
The pressure is real but explainable. FAIR Plan enrollment grew 43% between September 2024 and December 2025, with the January 2025 Los Angeles wildfires driving much of that increase as some carriers pulled back. More homes on a last-resort plan, after years of catastrophic losses, means higher costs to keep claims payable.
The wider market has felt it too. A June 2026 Stanford study found California homeowners insurance premiums have risen 84% since 2020. But the strategy now shaping these rates is also the mechanism designed to stabilize that market - and there are early, if modest, signs of private carriers re-entering it.
The Marin and San Francisco picture
This is where local knowledge earns its keep, because the two markets we serve sit at opposite ends of the risk map.
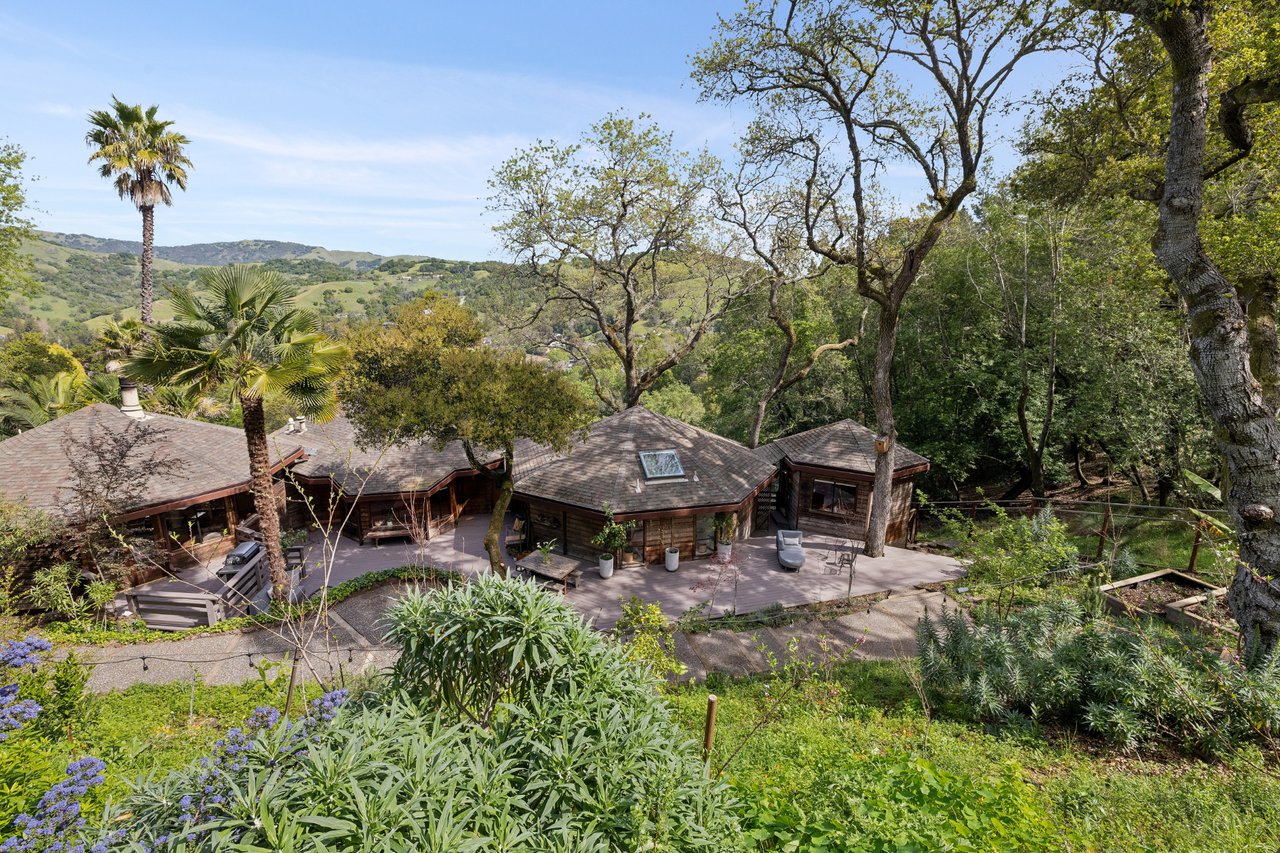
In West Marin, the effect lands most directly - in the coastal and wildland communities of Stinson Beach, Bolinas, Inverness, Point Reyes Station, Woodacre, and the San Geronimo Valley. These remain among the most coveted places to live anywhere in Northern California, and demand for them hasn't cooled. What's shifted is that buyers here now weigh insurability alongside price and view, confirming coverage as part of their decision rather than an afterthought at closing.
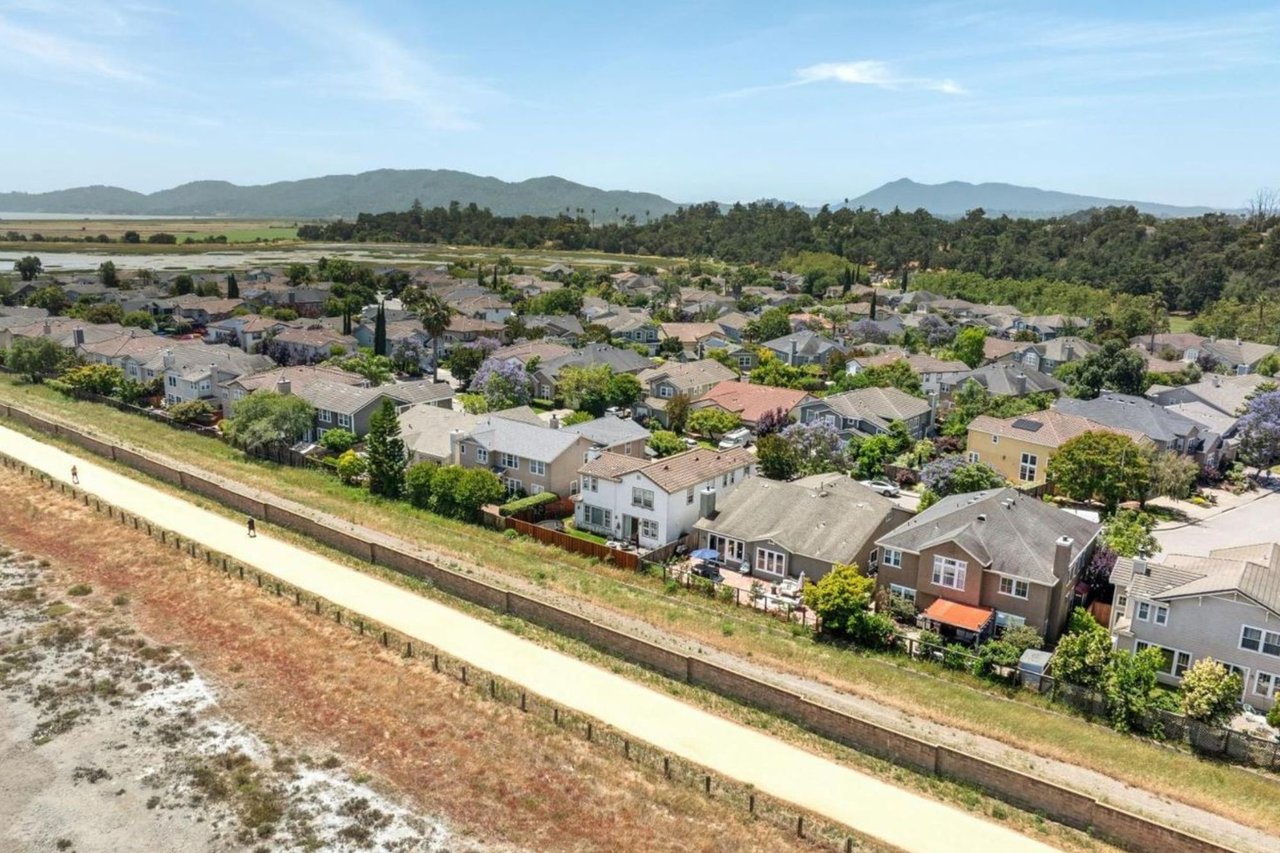
The contrast with Marin's bayside corridor is instructive. In Tiburon, Belvedere, Larkspur, Corte Madera, and much of San Rafael, wildfire exposure is far lower, and insurance tends to remain a routine cost rather than a deciding factor. San Francisco's dense urban housing stock carries the least exposure of all - for most city buyers, this change will be barely perceptible. Knowing which side of that line a property falls on is half the work.
What this means if you're buying, selling, or renewing
If you're buying in a higher-risk area, bring insurance to the front of the process. Confirming what coverage is available, and at what cost, before you're in contract keeps your timeline clean and removes the single most common late-stage surprise.
If you're selling, a home that's demonstrably easy to insure is a real advantage. California requires insurers to offer mitigation discounts under its "Safer from Wildfires" standards - documented defensible space, a five-foot ember-resistant zone around the structure, Class A roofing, and screened vents aren't just safety upgrades, they're selling points worth highlighting.
And if you already own, this fall is a natural moment to review your renewal and the mitigation credits you may qualify for. As carriers cautiously return to the market, a growing number of households are also finding a path back from the FAIR Plan to standard coverage.
Looking ahead
Insurance has graduated from a closing-day formality to a meaningful part of Bay Area real estate strategy - most of all across Marin's beautiful, fire-aware communities. The owners and buyers who come out ahead are simply the ones who understand their options early and treat home hardening as part of a property's value.
If you're considering a move in Marin or San Francisco and want to talk through how insurance fits your plans, we'd be glad to help you think it through. It's exactly the kind of guidance we're here for.
Sources: KRCR News, Insurance Business Magazine, Consumer Watchdog, Stanford University, CBS News Sacramento